
The blog
Notes on research, market microstructure, and the systems we build.
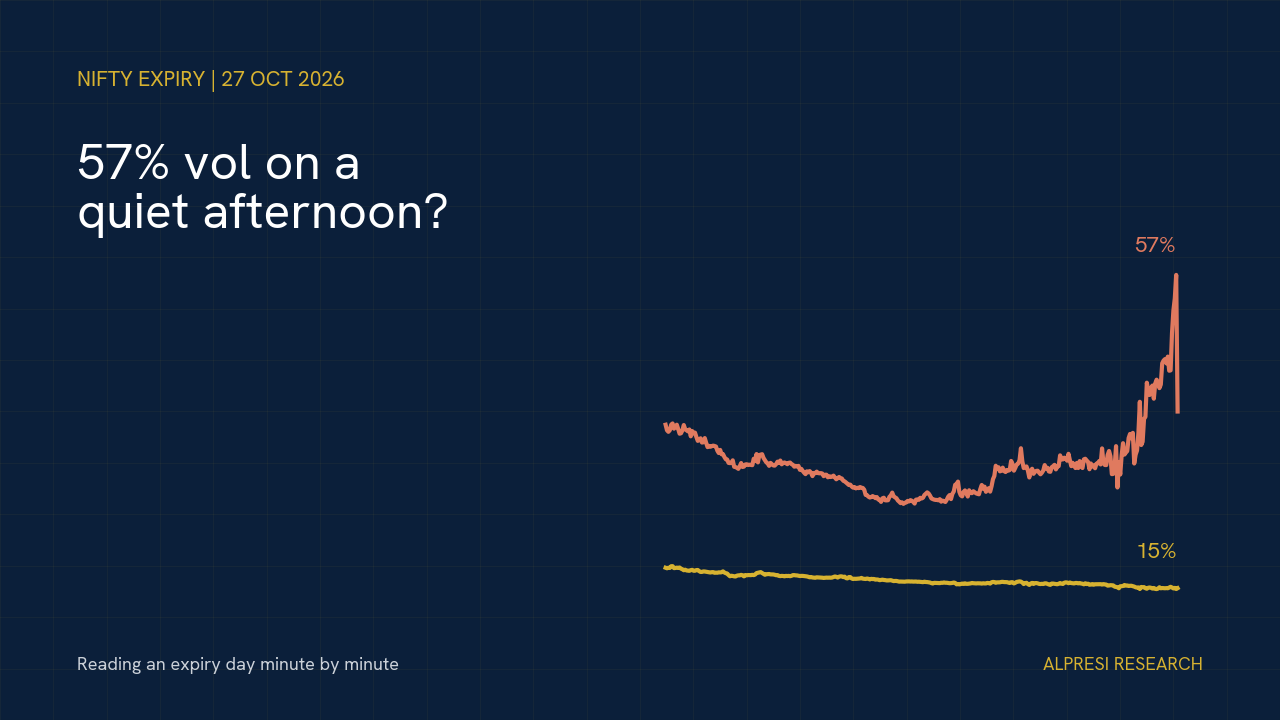
🔍 57% Volatility on a Quiet Afternoon? Reading NIFTY's 27 October Expiry Minute by Minute
At 15:20 on NIFTY's 27 October expiry, a typical ATM IV readout showed 57%. By 15:28 it showed 0.4%. The options were …
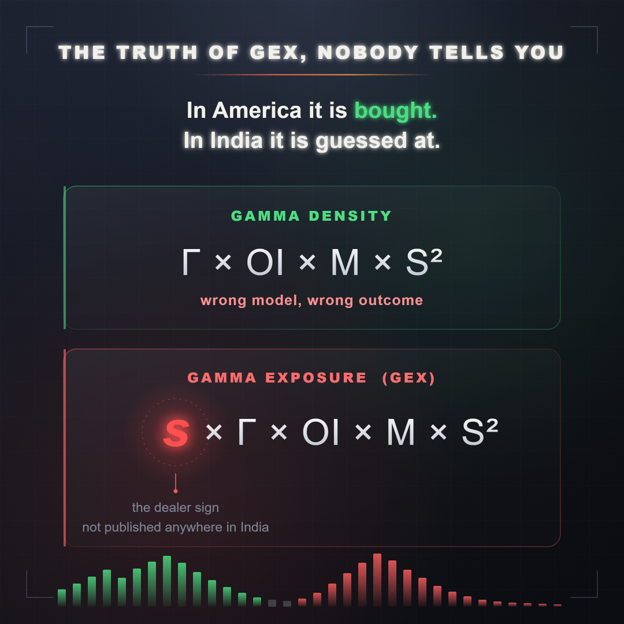
🔍Why Dealer Gamma Exposure GEX / Gamma Density Charts Don't Mean What They Claim in India.
🔍 Why "Dealer Gamma Exposure GEX"/"Gamma Density" Charts Don't Mean What They Claim in India.

📊 Delta-Gamma-Theta-Vega Hedging: Managing Spot, Time, and Volatility Risk: The Mathematical Engine Behind Professional Options Trading
📊 Delta-Gamma-Theta-Vega Hedging: Managing Spot, Time, and Volatility Risk: The Mathematical Engine Behind Professional Options Trading

🚨 The Mechanics of Gamma (GEX) : How Dealer Hedging Actually Moves Markets
🚨 The Mechanics of Gamma (GEX) : How Dealer Hedging Actually Moves Markets
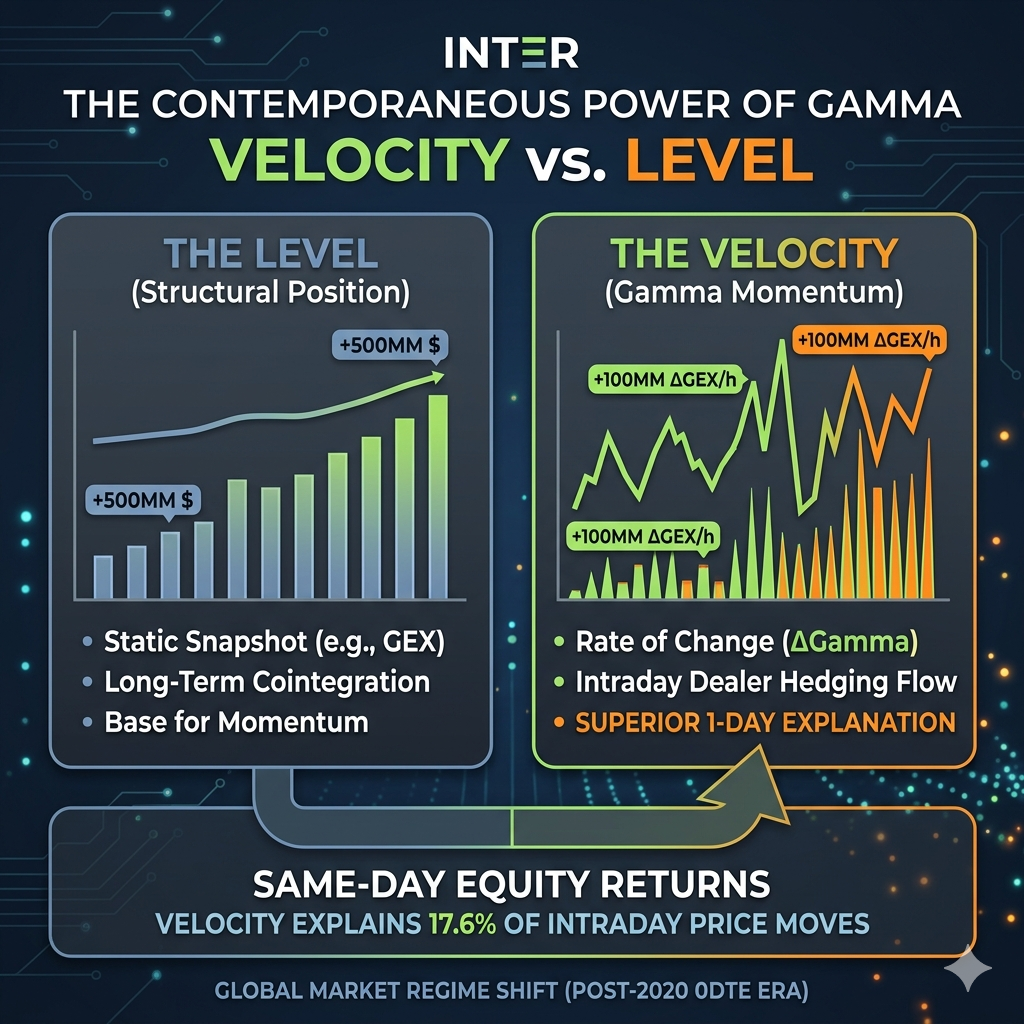
💼The Contemporaneous Power of Dealer Gamma: Why Gamma Positioning Momentum Explains Same-Day Equity Returns Better Than Its GEX Level
📊 The Contemporaneous Power of Dealer Gamma: Why Gamma Positioning Momentum Explains Same-Day Equity Returns Better Than Its GEX Level.

🔍Risk-Neutral Densities: Extracting and Interpreting Market-Implied Probability Distributions from Option Prices
🔍 Risk-Neutral Densities: Extracting and Interpreting Market-Implied Probability Distributions from Option Prices A Quantitative Perspective on One of Finance's Most Powerful Tools